

State of the Market: CLARITY Stalls, Fed Hikes
State of the Market | September 10 - September 16, 2026
State of the Market: CLARITY Stalls, Fed Hikes

Introduction
State of the Market | September 10 - September 16, 2026
Talos State of the Market is a weekly view of market structure, venue activity, derivatives positioning and flows across the digital asset landscape.
Weekly Pulse
CLARITY Stalls, Fed Hikes
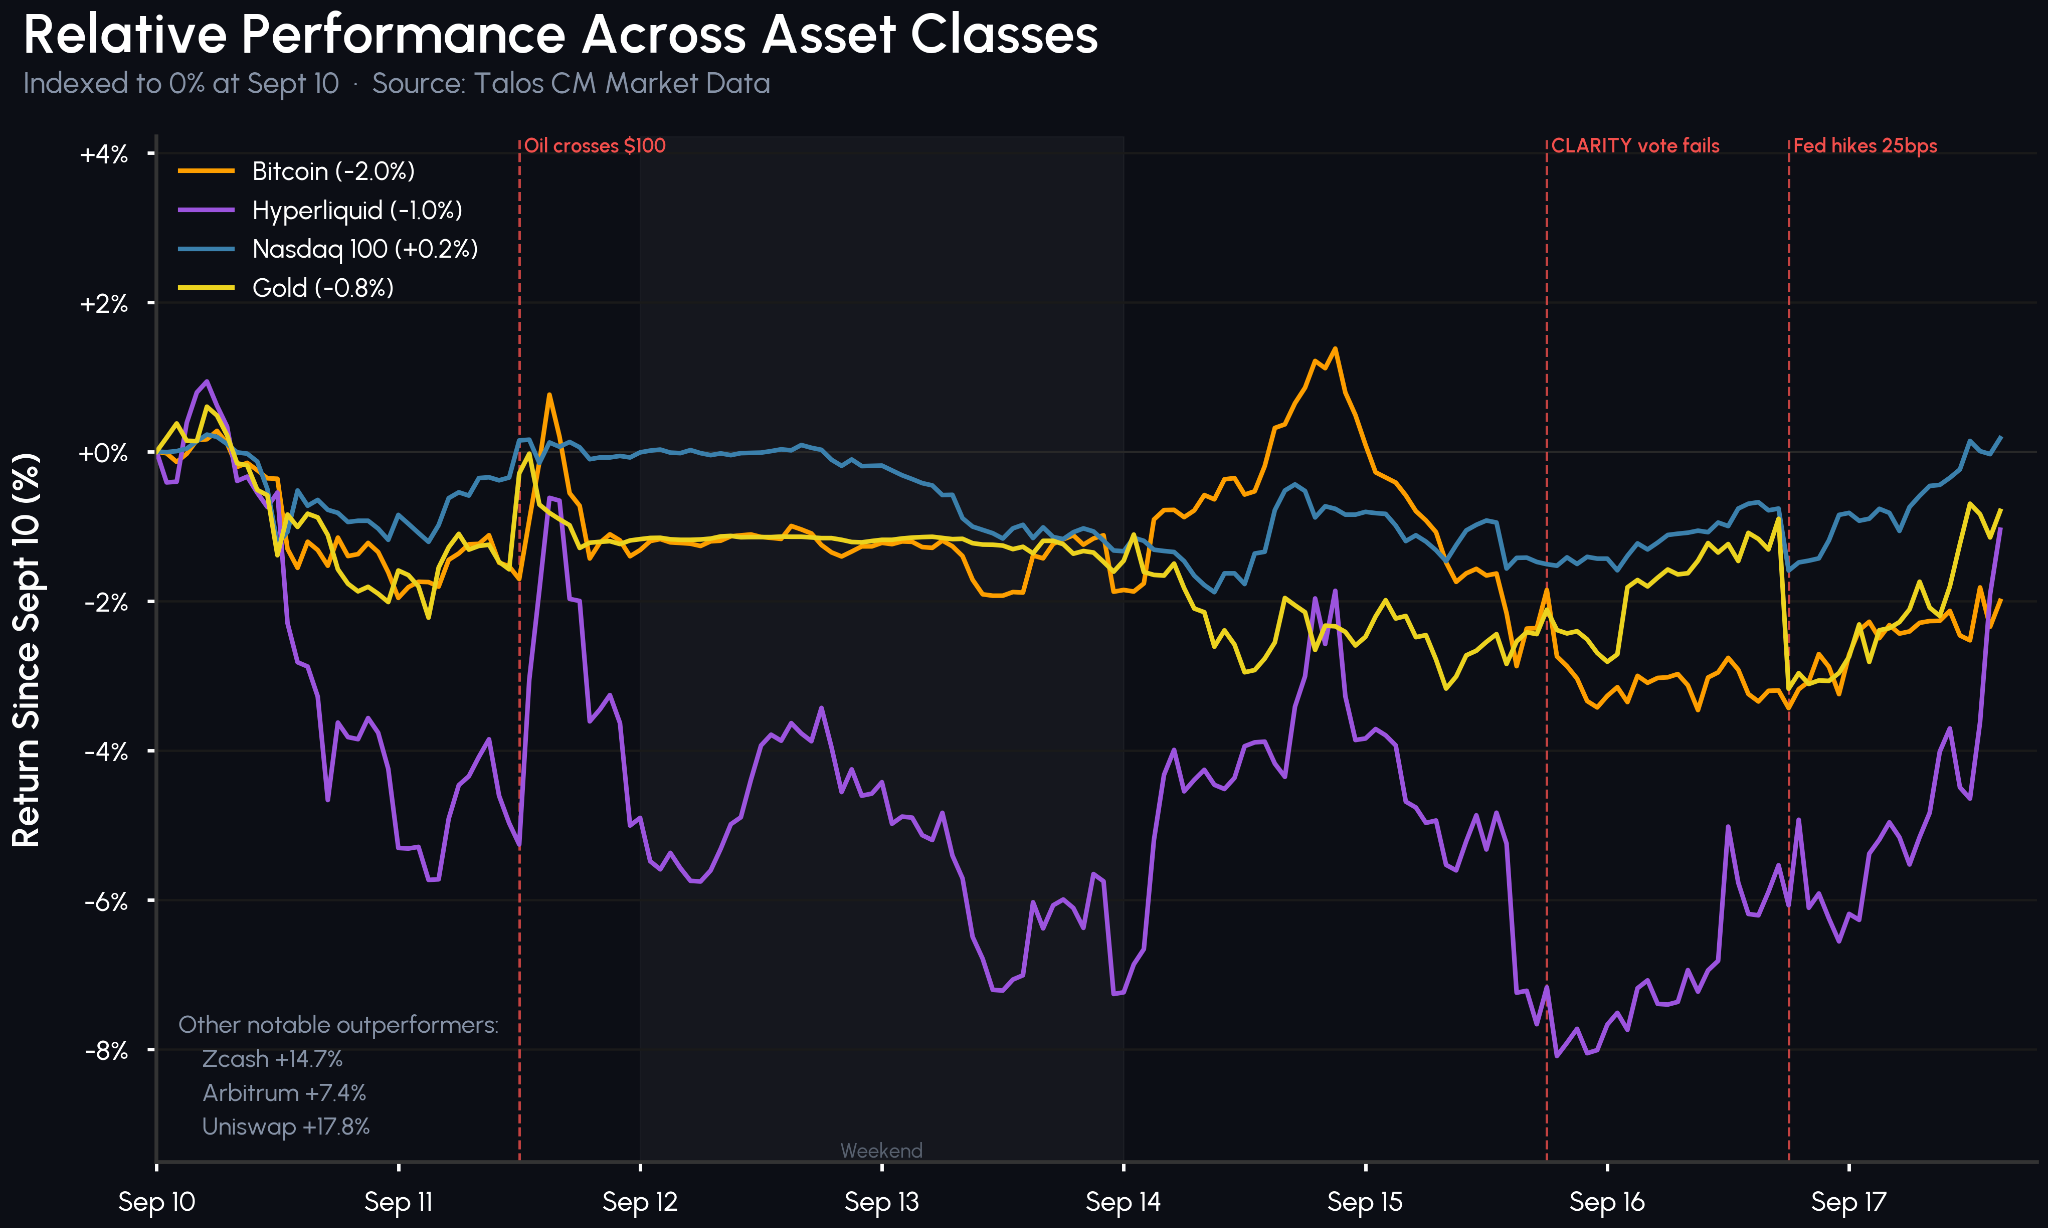
As widely telegraphed by markets, the Federal Reserve raised interest rates by 25bps for the first time in three years. While the decision itself was well anticipated, guidance pointed to more tightening ahead, with 16 of 18 participants seeing another hike this year in efforts for a "timelier" return of inflation to the Fed's target. Stocks rose and yields eased in the aftermath, a reversal from earlier in the week when semiconductor and hardware equities sold off sharply after calls from AI lab leaders to slow frontier development.
In digital asset markets, the CLARITY Act fell short of the 60 votes needed to advance through the Senate. BTC gave back its initial rally toward $79K without triggering a major drawdown despite a double whammy of seemingly bad news for crypto. With Congress stalled, agencies moved fast. Just two days after CLARITY's failure, the SEC granted a five-year "Innovation Exemption" allowing tokenized stocks, backed 1:1 with full voting and dividend rights, to trade onchain without venues registering as exchanges, provided issuers retain the right to block third-party tokenization of their own shares. The exemption notably excludes synthetic products, which cover most of today's onchain equity activity, leaving the SEC's stance on that still unresolved.
Meanwhile, Kraken's parent company Payward announced plans to bring CFTC-regulated perpetual futures to US clients through Hyperliquid's permissioned HIP-3 framework. Circle also launched Arc, its Layer-1 blockchain, on mainnet, with BlackRock, Visa and Mastercard among its founding validators and apps including Aave and Morpho live from day one.
Talos data showed caution building early in a dense week, with institutional investors running a 28% net buying tilt toward stablecoins ahead of the decision, even as hedge funds stayed net buyers against selling from systematic strategies. In the hour after the hike, perpetual futures flipped to net selling in BTC and ETH, though spot demand absorbed much of that pressure.
Market Performance
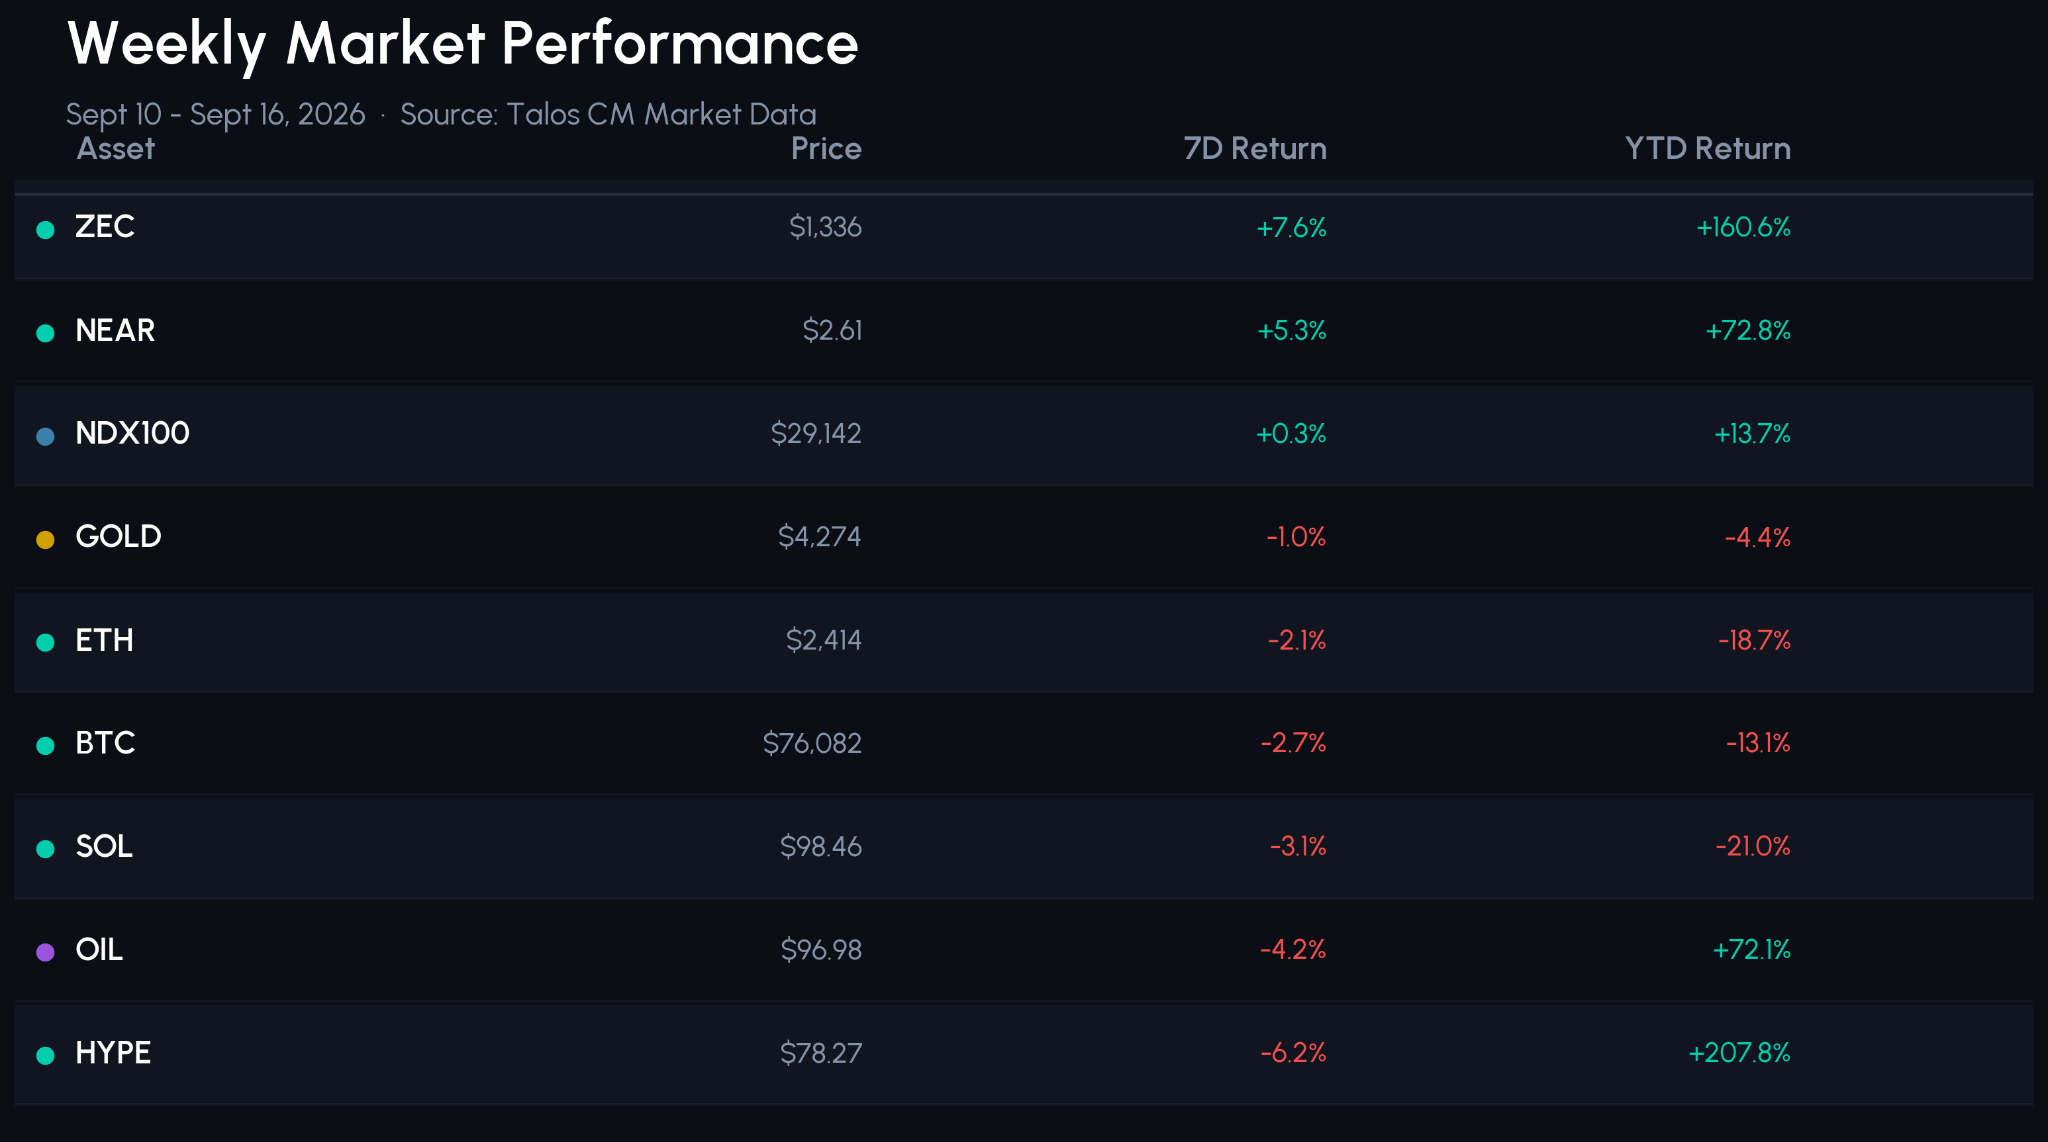
The total crypto market cap stands at $2.79T, down 2.3% over the past week. Bitcoin fell 2.7% on the week, underperforming the S&P 500 (flat), Nasdaq 100 (+0.3%) and gold (-1.0%) as the CLARITY Act failure and the Fed's rate hike weighed on risk appetite. Breadth was thin, with only 11 of the top 50 assets gaining and declining names outweighing advancers roughly 10-to-1 by market cap.
- Crypto Majors: BTC -2.7% | ETH -2.1% | SOL -3.1%
- Top Gainer: Zcash (ZEC) up 7.6% on the week and now +160.6% YTD
- Uniswap (UNI) and Arbitrum (ARB), up 7.7% and 10.4% respectively, as Robinhood Chain's record trading activity continued to feed fee revenue to both underlying protocols.
Flows
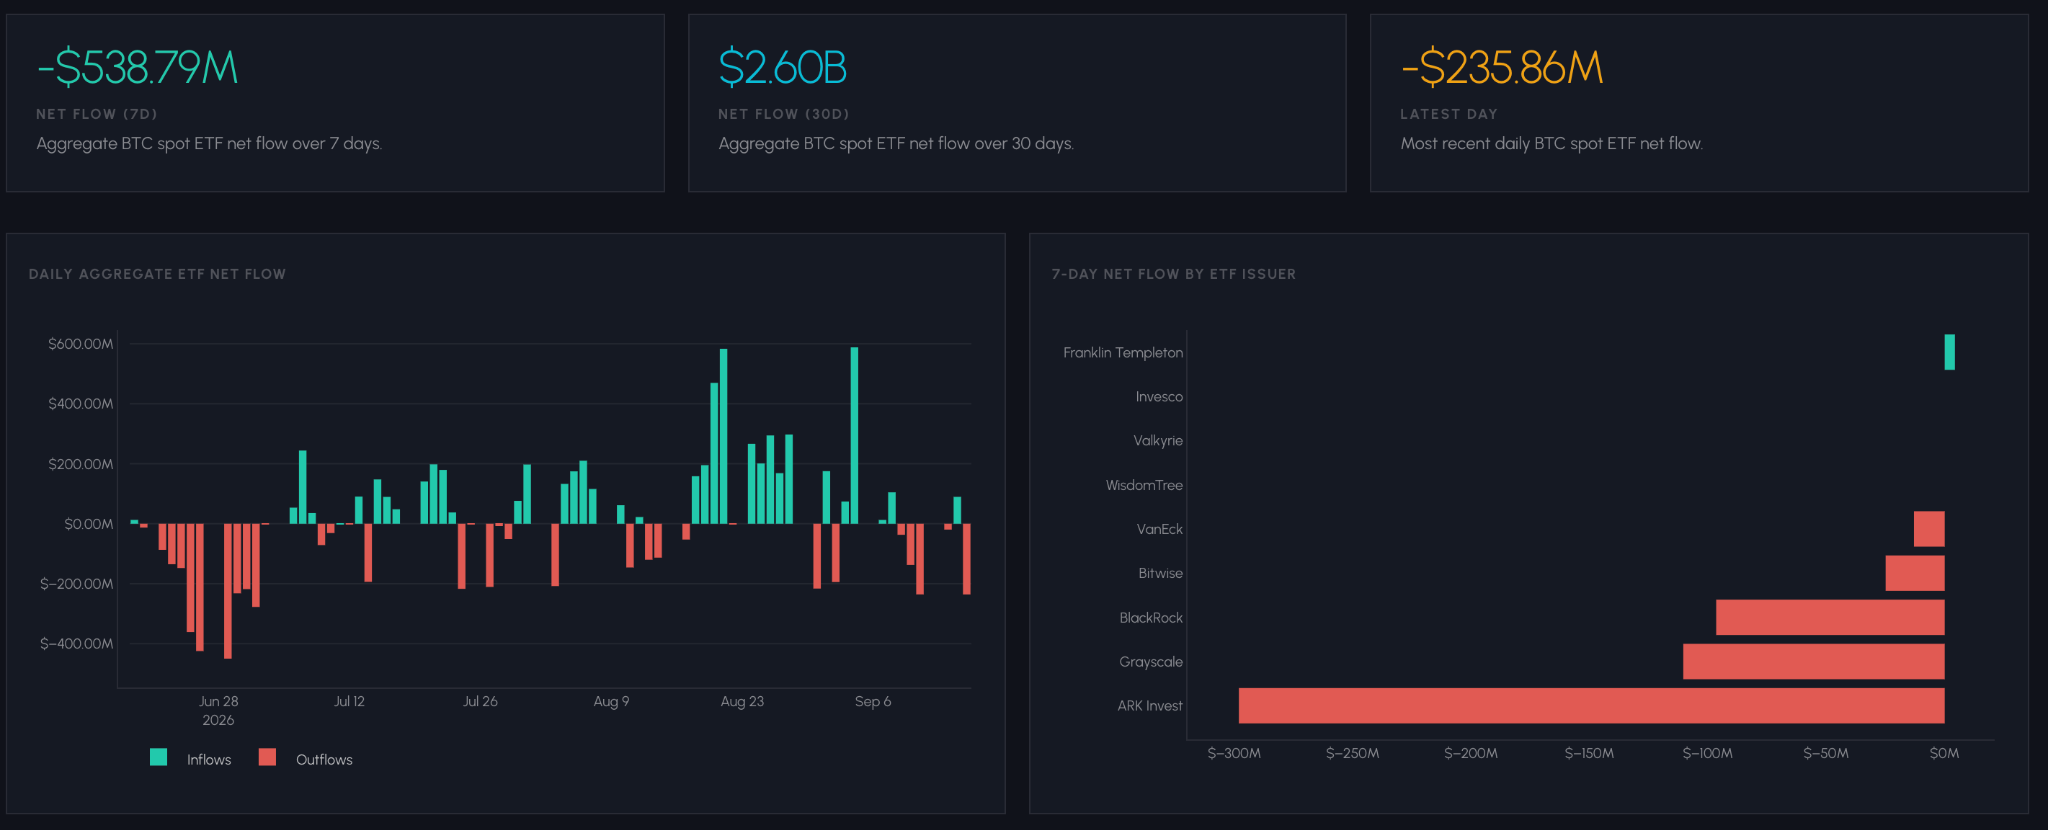
- Spot Bitcoin ETFs saw $539M in net outflows over the past week, reversing last week's $742M inflow as institutions pulled back ahead of the Fed decision, though the 30-day total remains positive at $2.6B.
- Exchange balances also drew down, with BTC deposits net negative by $548M and ETH by $272M on the week, a slower pace of outflow than the prior week, but extending a 30-day net outflow of $5.45B in BTC.
- Stablecoin supply contracted by ~$809M, driven by a drawdown in USDC, a reversal from last week's growth and a sign of some liquidity pulling back from the onchain ecosystem.
Spot & Derivatives Activity
- Spot volume across exchanges rose 4.0% WoW to $200.9B while futures volume rose 6.3% to $1.07T. Open interest was roughly stable in native terms for BTC and ETH, with a modest USD decline (BTC -1.6% to $44.4B, ETH -1.2% to $26.0B) mostly reflecting price rather than a shift in positioning. Funding rates ticked up to +6.4% annualized.
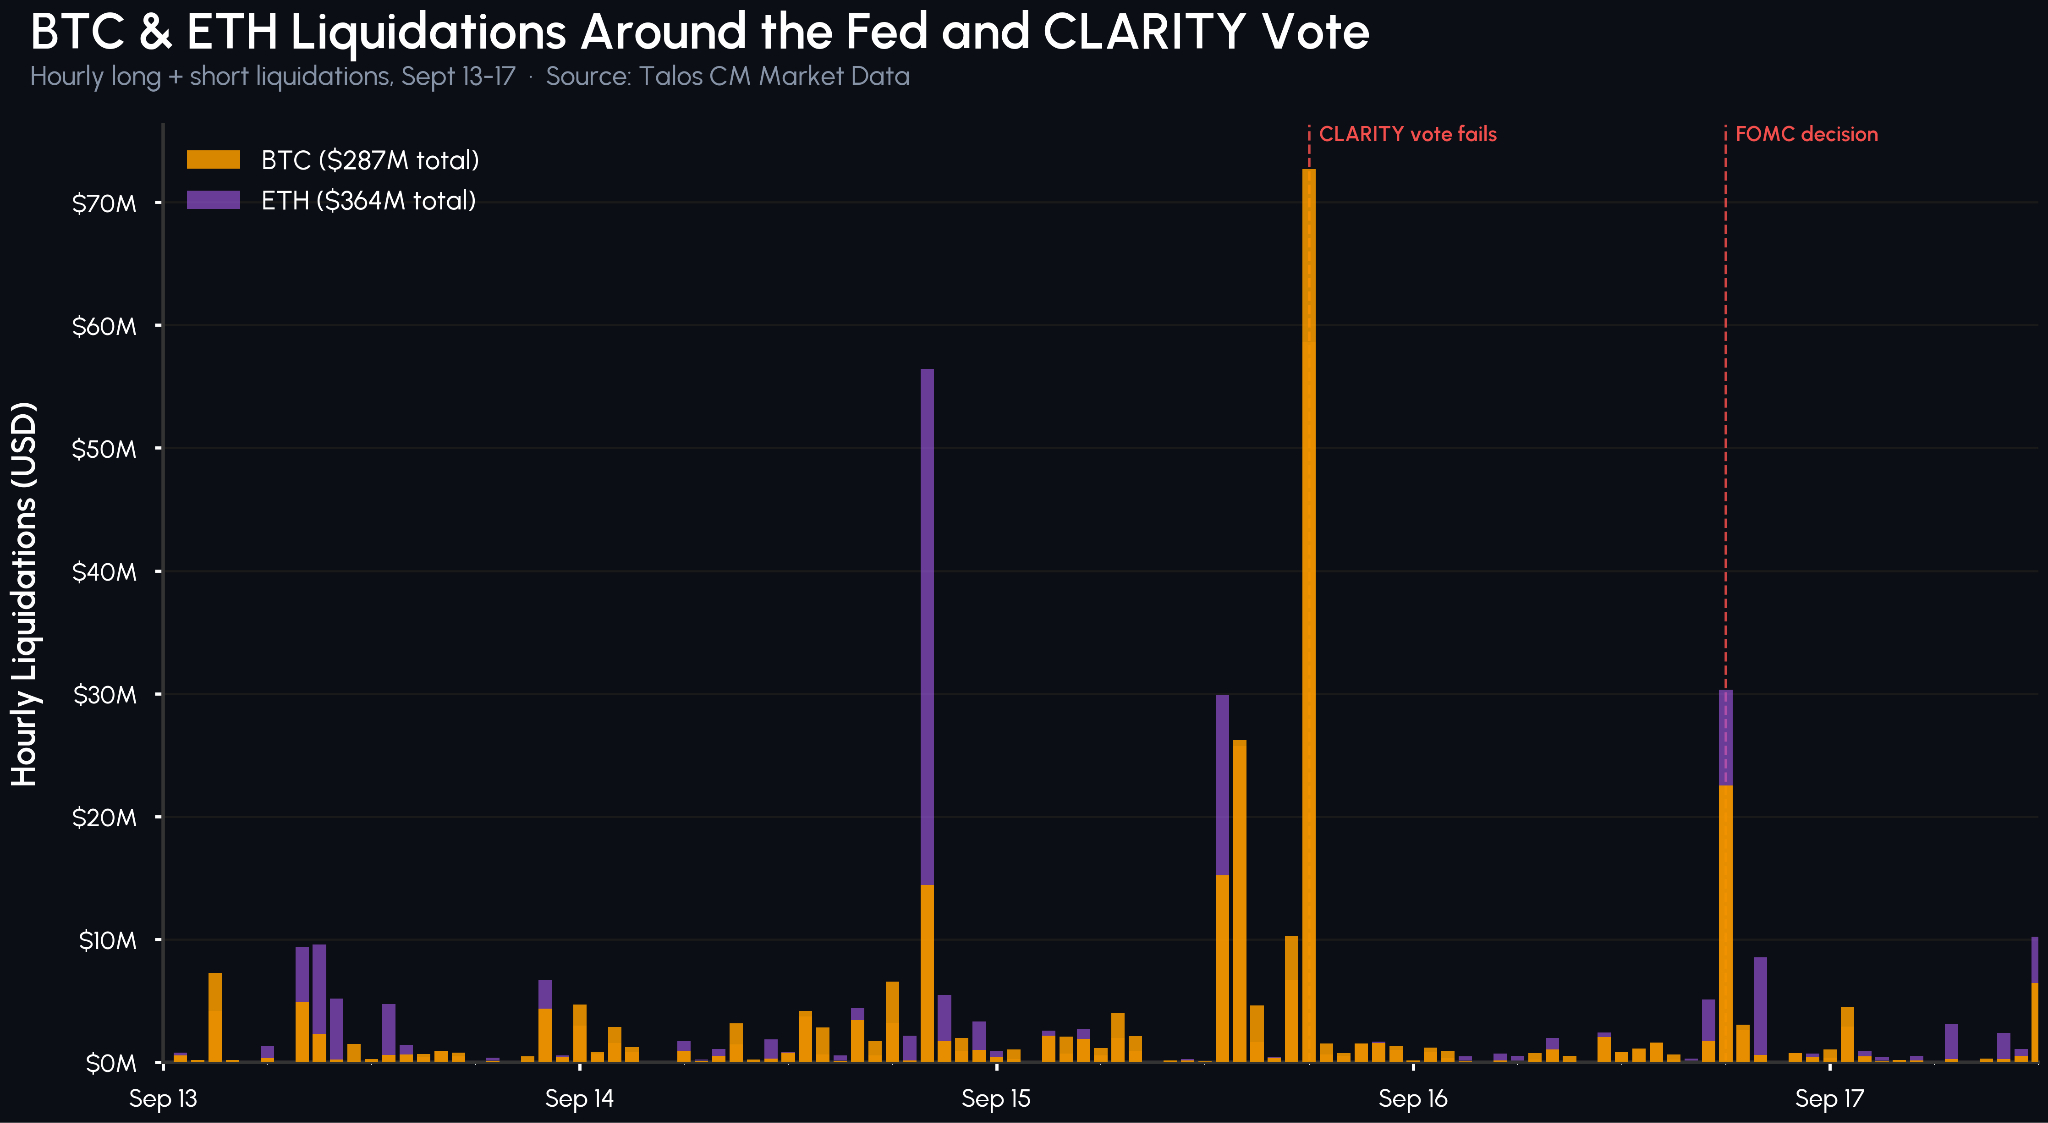
- Liquidations picked up sharply, concentrated almost entirely in the hour the CLARITY vote failed, with ETH liquidations up 82.9% WoW to $545.5M and BTC up 15.9% to $398.3M
Disclaimer: Talos Global, Inc. and its affiliates ("Talos") is not an investment advisor or broker/dealer. This information does not constitute an offer to buy or sell, or a promotion or recommendation of, any digital asset, security, derivative, commodity, financial instrument or product or trading strategy. This information is not intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. This information is subject to change without notice. It is provided only for general informational, illustrative, and/or marketing purposes and is not intended for retail clients. The information provided was obtained from sources believed to be reliable at the time of preparation, however Talos makes no representation as to its accuracy, suitability, non-infringement of third-party rights, or otherwise. Talos disclaims all liability, expenses, or costs arising from or connected with the information provided. All content is provided for informational and illustrative purposes only. It does not represent firm offers, executable prices, or commitments of any kind, and should not be relied upon as indicative of current or future market prices or the terms on which any transaction may be executed.
Subscribe
If you’d like to get State of the Market in your inbox, please subscribe below.
Latest insights and research

Request a demo
Find out how Talos can simplify the way you interact with the digital asset markets.